Summary: If you are searching for individual or family health insurance during Open Enrollment, this article is for you. The main differences between private and ACA health insurance plans come down to where you enroll, whether you can use financial assistance, and which plans are available to you. Compare actual premiums, networks, and benefits before choosing.
What Are You Comparing When You Shop for Coverage?
If you’re trying to understand the differences between private and ACA health insurance plans, you may be comparing a quote from an insurer with a plan on Covered California. The two listings can make it look as though you’re choosing between two kinds of insurance. What you’re really comparing is two ways to buy individual or family coverage.
An off-exchange plan is one you buy directly from an insurer, either on your own or with a broker’s help. An on-exchange plan is one you buy through Covered California, the state’s health insurance marketplace. The same insurance companies provide the coverage in both cases. The Affordable Care Act, or ACA, sets standards that apply to comprehensive individual plans sold through either route.
In our earlier article, When Private Health Insurance Makes Sense for Individuals in Southern California, we looked at when buying directly might suit your situation. Here, we’ll look more closely at what can change when you compare two plans, from the amount you pay each month to where you can get care.
Differences Between Private and ACA Health Insurance Plans at a Glance
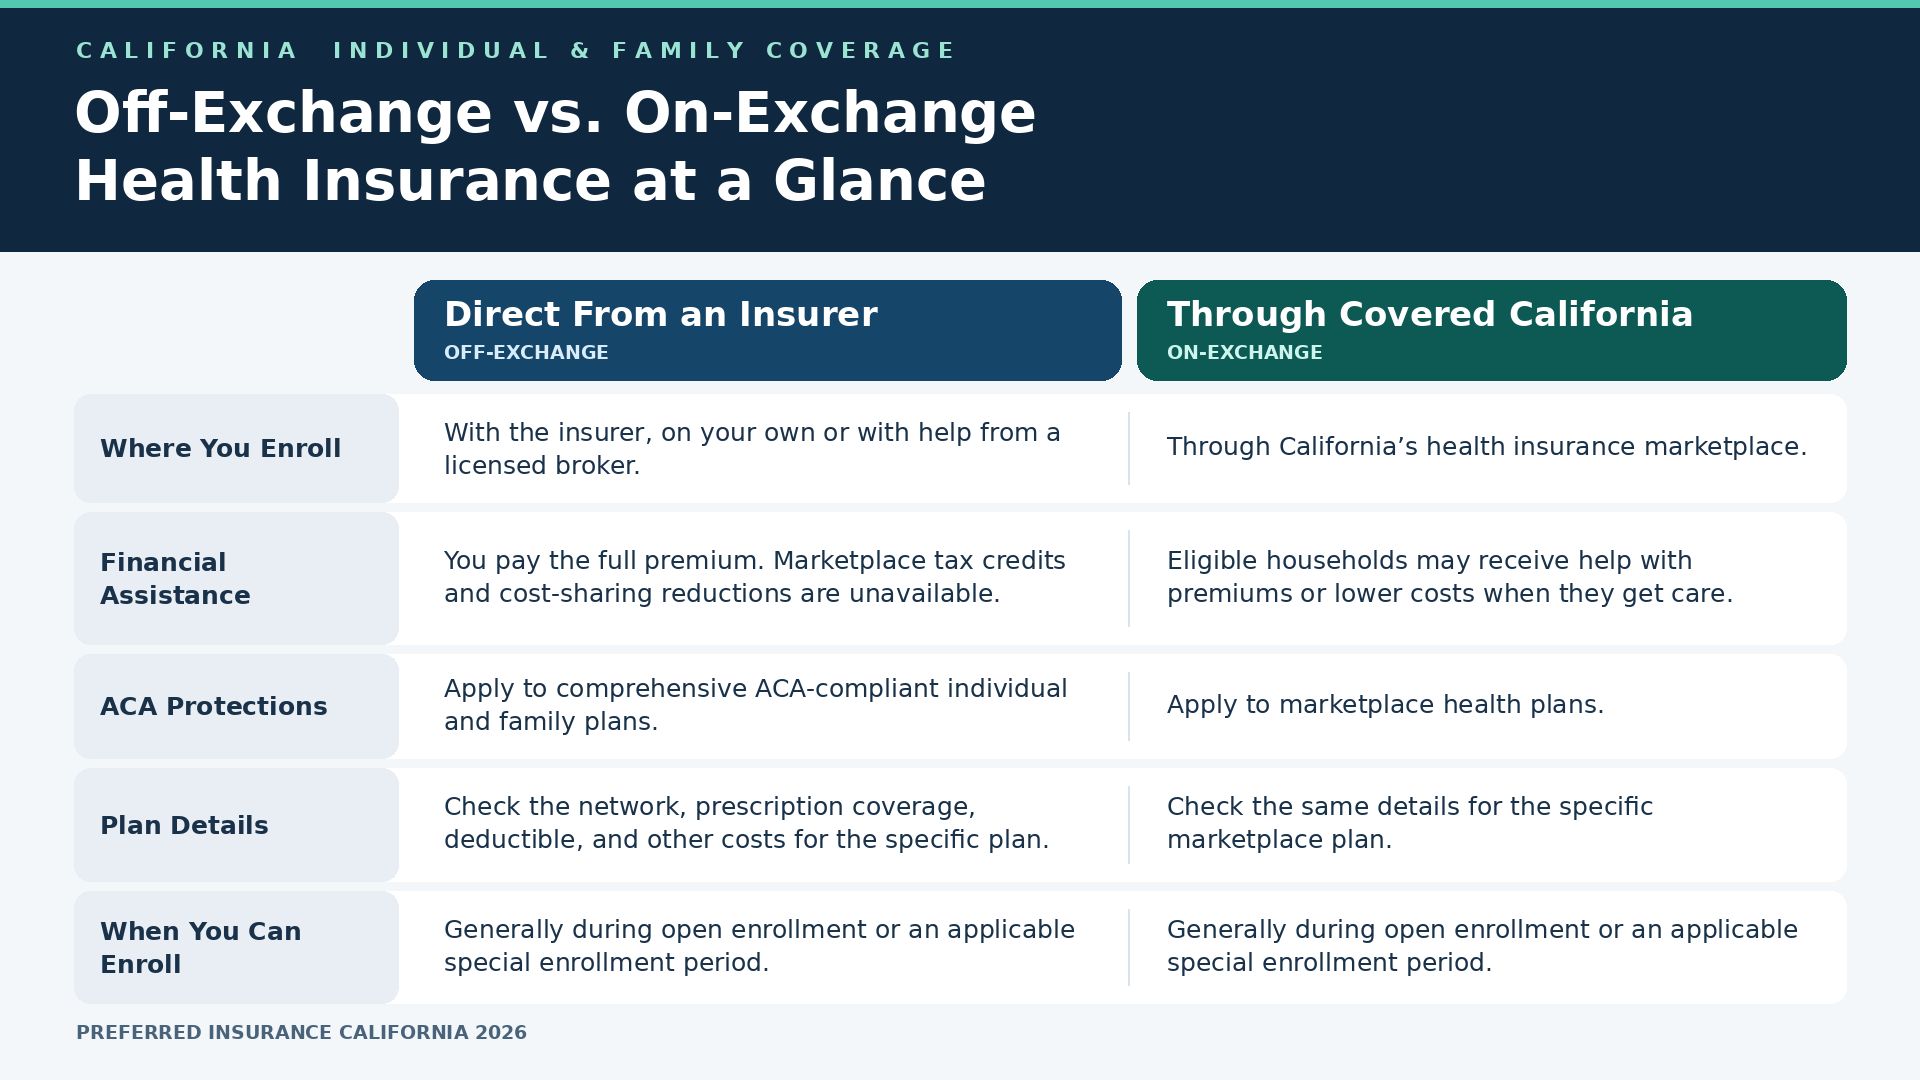
If you’re shopping for your own health insurance in California, you can buy a plan directly from an insurer or enroll through Covered California. Both routes offer private plans that follow Affordable Care Act (ACA) rules. The side-by-side comparison below shows how each route works, where financial help is available, and what to check before choosing a plan.
The buying route tells you where to enroll and whether marketplace financial help is available. The plan documents tell you what you’re buying. That second part matters when two quotes are similar in price or show the same insurer’s name.
Compare What You Would Actually Pay
One of the most consequential differences between private and ACA health insurance plans is whether financial assistance can lower your costs. An off-exchange quote shows the premium you’d pay for that policy. When comparing it with a marketplace plan, use what you would actually pay after any premium assistance you qualify for.
There’s another cost to consider beyond the premium. Some eligible Covered California members who choose an Enhanced Silver plan pay less when they get care through reduced deductibles, copays, or other cost-sharing. If you qualify, compare those costs too. You can check the rules through Covered California’s financial assistance guide.
If you will be paying full price either way, compare the premiums side by side, then consider what each plan would cost you to use. A lower monthly price can be appealing, but if you regularly see a specialist or refill a prescription, the cost of that care can change how the two options stack up.
At Preferred Insurance California, we help Southern California individuals and families review the costs of the direct-purchase plans they’re considering. We can walk through what you’d pay to keep coverage and what you might pay when you need care.
Check the Exact Network and Prescription Benefits
Suppose you live in Oceanside and see a specialist elsewhere in San Diego County. You recognize the insurer on both quotes, and the specialist’s office says it accepts that insurer. You still need to confirm whether the specialist participates in the exact plan you’re considering, at the location where you receive care.
That’s one of the most commonly misunderstood differences between private and ACA health insurance. Buying directly doesn’t tell you how broad the network is. When you compare two plans, check the doctors, medical groups, and hospitals you actually use. If seeing an out-of-network provider matters to you, review the plan’s coverage and costs for that care.
Do the same for regular prescriptions. A formulary is the plan’s list of covered drugs. Finding your medication on it is a start, but you’ll also want to know what you would pay and whether the insurer requires approval before covering it. We can help you identify which details to verify before choosing a direct-purchase plan.
ACA Protections Apply to Comprehensive Coverage Bought Either Way
When people talk about the differences between private and ACA health insurance plans, they sometimes wonder whether buying directly changes how a pre-existing condition is treated. Comprehensive ACA-compliant individual plans sold directly by insurers share core protections with marketplace plans. For example, your health history cannot affect your eligibility for coverage or the premium an insurer charges you.
Plans can follow the same rules and still vary in ways that matter to you. Two plans may both cover prescription drugs, yet differ in what you pay for a specific medication. They may both cover specialist care, yet have different networks. Those differences become clearer when you compare the specific plans against your own care needs.
Check When the Plan Can Start
Buying directly from an insurer generally follows individual market enrollment windows. Having a baby, getting married, or losing job-based coverage may trigger a special enrollment period. Confirm the applicable deadline and effective date before relying on the new plan. See the California Department of Insurance’s guide to qualifying life events.
Timing matters especially if you’re moving from one policy to another. Ask when your existing plan ends, when the new plan takes effect, and whether the insurer requires a first premium payment to activate coverage. We can help you identify those questions as you consider direct enrollment.
Bring the Plans You’re Comparing
The differences between private and ACA health insurance plans get easier to sort through when you have specific options in front of you. Bring the quote or plan name, the monthly premium, and the doctors or prescriptions you’d like to check. If you’re replacing coverage, bring the date you need the new plan to start.
At Preferred Insurance California, we help you review available direct-purchase options and understand how each one fits your budget and care needs. If a question comes up after enrollment, you can come back to us for help working through the next step.
FAQs: Differences Between Private and ACA Health Insurance Plans in California
Private means buying directly from an insurance company and ACA refers to buying through Covered California. The main differences are where you enroll, whether you can use marketplace financial assistance, and which specific plans are available. Both routes can provide comprehensive coverage that follows ACA rules.
Marketplace premium tax credits apply only to eligible coverage purchased through Covered California. They cannot be applied to an off-exchange policy, even if the insurer also sells plans through the marketplace.
Yes. Check the network for the exact plan you’re considering and confirm the doctor’s participation at the location where you receive care. An office that accepts one plan from an insurer may participate in a different set of plans than you expect.
You can buy directly from an insurer on your own or work with a licensed broker. A broker can help you compare available plans and understand how the network, prescription benefits, and out-of-pocket costs apply to your decision.
Yes. Contact us with a quote you’re considering or a few details that matter to you, such as your budget or a doctor you want to keep. We can help you review available direct-purchase plans and identify the details to confirm before you enroll.